22 September 2026
Table of Contents
- What is Google Business Profile for insurance brokers?
- What is Google Business Profile for insurance brokers?
- Key Takeaways
- Why the map pack is critical for brokers
- How to claim, verify, and set up your profile correctly
- Choosing the right category for an insurance brokerage
- Writing a business description answering the real question
- Building reviews converting browsers into callers
- Posts, Q&A, and the profile features brokers leave unused
- Closing reflection
- Frequently Asked Questions
A small business owner in Roodepoort gets a letter from his insurer cancelling his commercial vehicle policy. He goes straight to Google and types "insurance broker near me". A map appears with three names, phone numbers he can tap, and star ratings from other business owners. One broker has forty-two reviews and lists commercial vehicle cover as a service. He calls that broker within the minute. Two other brokers in the same suburb appear nowhere on that map. Their offices are closer. Neither has a Google Business Profile.
What is Google Business Profile for insurance brokers?
Google Business Profile (formerly called Google My Business) is a free listing Google uses to display your brokerage on Search and on Maps when someone nearby searches for insurance help. It isn't your website. It is the panel appearing beside or above the search results — showing your name, address, phone number, office hours, services, photos, and client reviews — before anyone decides whether to click through. For an insurance broker, that panel is often the first thing a prospective client sees, and frequently the only thing they look at before picking up the phone.
What is Google Business Profile for insurance brokers?
Google Business Profile (formerly Google My Business) is a free listing Google uses to display your brokerage on Search and Maps when someone nearby searches for insurance help. It isn't your website. It is the panel appearing beside or above the search results, showing your name, address, phone number, office hours, services, photos, and client reviews, before anyone decides whether to click through. For an insurance broker, that panel is often the first thing a prospective client sees, and frequently the only thing they look at before picking up the phone.
Key Takeaways
- A verified Google Business Profile puts your brokerage on the map when local clients search for short-term, commercial, or life cover.
- The category "Insurance Broker" is available in Google's taxonomy and should be your primary category, with secondary categories added where your lines of cover warrant them.
- Complete profiles, with accurate hours, services, photos, and a steady flow of reviews, consistently outperform thin or unclaimed listings for local placement.
- Responding to every review, positive and negative, signals to Google and to prospective clients that your practice is active and accountable.
- Posts, Q&A answers, and product listings inside the profile let you answer the questions clients are already asking before they reach your website.
- Insurance brokers in South Africa operate in a high-trust, high-consideration category where a well-maintained profile can be the difference between a phone call and a scroll past.
Why the map pack is critical for brokers
Insurance buying is a considered decision, but the search starting it is often urgent. When a client's vehicle is written off and their broker is uncontactable, or when a newly registered business owner realises they have no cover, they search immediately and call whoever appears first. The local pack, the map showing three businesses at the top of Google, captures that urgency before any website does.
Research on local search intent confirms Google Business Profile is one of the strongest local SEO signals available, and for service businesses the map listing drives more direct contact than the organic results below it. For insurance brokers specifically, the stakes are higher than for a restaurant or a retailer: a client choosing cover is choosing someone they will call on claims day, so proximity signals and visible trust indicators, reviews, response rate, complete information, do most of the persuasion work. A broker without a profile is simply absent from that moment. The enquiries go elsewhere, and the revenue compounds for whoever does appear.
How to claim, verify, and set up your profile correctly
Claiming a Google Business Profile is straightforward, but the verification step catches many brokers off guard. Go to the Google Business Profile manager, search for your brokerage by name, and claim it if a listing already exists. If it doesn't exist, create one from scratch. Google will then ask you to verify ownership, typically by post, phone, or video. Until verification is complete, the profile isn't live and won't appear on Maps.
Once verified, the setup work begins. Google's own documentation on establishing business details confirms accurate and consistent name, address, and phone number information is foundational to how Google understands and surfaces a business. For a broker, this means the name on the profile must match the name on your Financial Sector Conduct Authority registration and on your website exactly: no abbreviations, no added descriptors. The address must be the office clients can visit. A home address listed on a profile for an FSCA-licensed brokerage raises questions Google can't answer and clients won't wait around to resolve.
Choosing the right category for an insurance brokerage
Google's category system is more specific than most brokers realise. The primary category for most brokerages is "Insurance Broker", and this is the correct choice. Published Google Business Profile category lists confirm "Insurance Broker" as a distinct category, separate from "Insurance Company", "Insurance Agency", and "Insurance Attorney". Using the wrong primary category is a common error, and it costs placement: Google uses the category to decide which searches a profile is relevant for.
Secondary categories add context for brokers offering multiple lines of cover. A brokerage handling short-term personal lines, commercial cover, and life insurance may add relevant secondary categories to signal that range to Google. Secondary categories should reflect actual services, though. Adding categories for products you don't actively place creates a mismatch between the profile and the enquiries it generates, and those misdirected enquiries erode review quality over time. Google's Business Profile APIs documentation notes category selection directly affects which searches trigger a profile's appearance.
Category selection comparison for a South African insurance broker
| Profile Type | Primary Category | Secondary Categories | Search Visibility |
|---|---|---|---|
| Short-term personal lines only | Insurance Broker | None | Personal lines searches |
| Commercial and personal lines | Insurance Broker | Commercial lines | Broader commercial visibility |
| Life, short-term, and commercial | Insurance Broker | Life insurance, commercial | Widest local coverage |
| Unclaimed or miscategorised | Insurance Company | None set | Reduced or missing |
Writing a business description answering the real question
The business description field inside a Google Business Profile allows up to 750 characters. Most brokers leave it blank or paste in their website tagline. Neither approach does any work. The description is the one place in the profile where you can write directly to the client standing at their decision point.
A useful description for an insurance broker in South Africa names the lines of cover offered, the types of clients served, the service area, and what makes contact worthwhile. "We place short-term cover for small and medium businesses across Gauteng, including commercial vehicle fleets, office contents, and liability. We also advise on personal lines for our clients' households and vehicles. Our office is in Centurion and we meet clients by appointment or on site" is a description matching the search a prospective client runs, telling them whether they are in the right place, and giving Google enough signal to surface the profile for relevant queries.
What to avoid: generic language ("we provide excellent service"), superlatives ("the best insurance broker"), and claims about pricing that can't be substantiated. The Financial Advisory and Intermediary Services Act governs how brokers may present themselves, and a Google Business Profile is a public-facing marketing asset subject to those constraints.
Building reviews converting browsers into callers
Reviews are the most visible trust signal on a Google Business Profile, and for insurance brokers they carry a significance other service categories don't share. Choosing an insurance broker isn't like choosing a cleaner or a plumber. Clients are handing over responsibility for their most significant financial exposures, so the social proof of other business owners or households vouching for a broker's claims handling and responsiveness is a genuine decision factor.
The mechanics of review acquisition are straightforward. After a successful placement or renewal, send the client a direct link to your Google review page. A one-paragraph email explaining a review helps other clients find the practice, with a single tap to the review form, converts at a much higher rate than a verbal request at the end of a meeting. Profiles with a steady and recent flow of reviews consistently outperform those with a large number of older reviews and no new activity. Recency tends to outperform volume once a profile reaches a credible baseline.
Responding to reviews is equally consequential. A broker answering every review, thanking the client, noting what line of cover the review relates to, and in the case of a negative review acknowledging the experience and offering a path to resolution, signals to Google the profile is actively managed. It also signals to every prospective client reading those reviews that this broker handles problems rather than ignoring them, which is precisely the quality a client values before a claim.
Posts, Q&A, and the profile features brokers leave unused
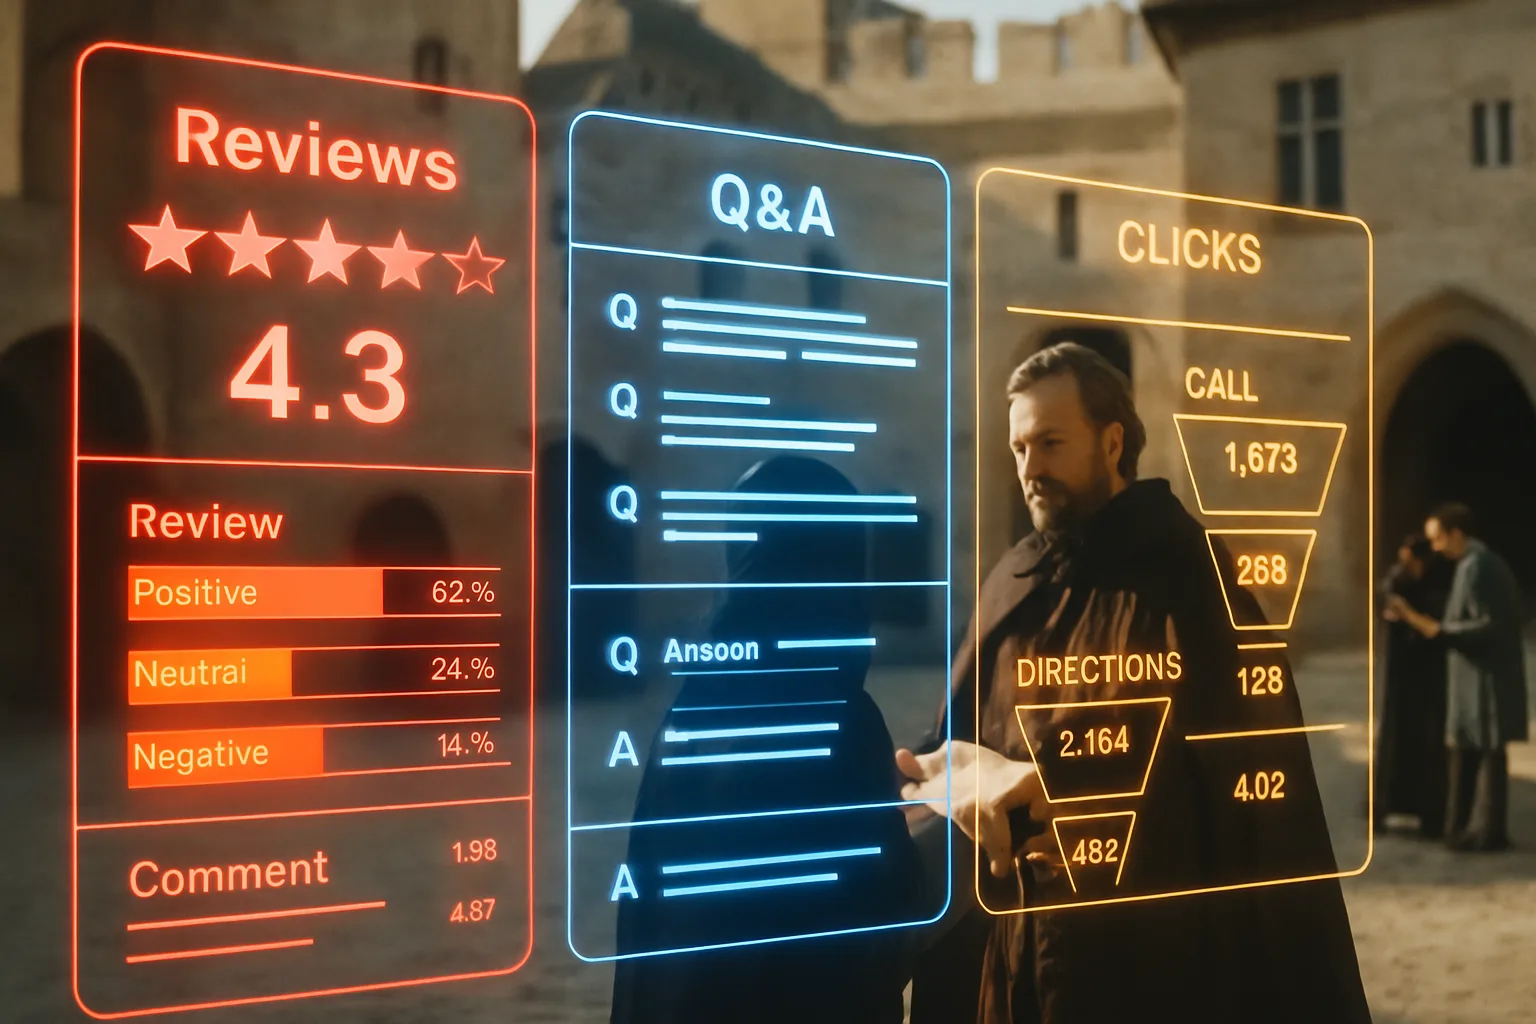
Most insurance brokers claim their profile and stop there. The features keeping a profile active and visible are rarely used, and that is the gap worth occupying. Google Business Profile allows brokers to publish posts, short updates of 100 to 300 words, appearing directly on the profile in search results. Posts expire after seven days unless they are events, so the discipline of posting weekly or fortnightly is the barrier. The content doesn't need to be elaborate: a post about renewal season reminders, a note about a common claims mistake, or a straightforward explanation of the difference between fleet and hired-vehicle cover gives Google a reason to treat the profile as current and gives visiting clients a reason to stay longer.
The Q&A section is even more valuable and almost universally ignored. Google allows anyone to post a question on a business profile, and anyone to answer it. For a broker, this means potential clients or competitors can post questions sitting unanswered. The correct approach is to populate the Q&A section yourself with the questions your clients actually ask. Questions like "Do you offer cover for a commercial delivery fleet?" or "What types of policies do you advise on?" mirror the real queries clients type into search. How a business presents itself across its public listings affects how easily Google can surface it for the right searches. Answering your own Q&A with clear, accurate responses is one of the lowest-effort, highest-return moves available on the profile.
Closing reflection
A Google Business Profile doesn't replace a broker's reputation. It makes that reputation visible to the clients who haven't met you yet. The clients finding you through a phone referral already trust you before they call. The clients finding you through Google are measuring you against every other name on that map, and they are doing it in under a minute. What your profile shows in that minute determines whether they tap your number or the one below it. That isn't a technical question. It is a practice management question with a practical answer.
You shouldn't have to lose local clients to brokers with thinner practices and better-maintained listings. With Zahavah Studio you won't.
Contact Zahavah Studio to set up and optimise your Google Business Profile so your brokerage appears when clients in your area are searching for cover.
Insurance brokers frequently have questions about the more specific mechanics of the profile, from how categories work to whether multiple offices need separate listings. The answers below address the most common ones.
Frequently Asked Questions
What is a Google Business Profile, and why do I need one as an insurance agent?
A Google Business Profile is a free listing controlling how your brokerage appears on Google Search and Google Maps when someone nearby searches for insurance help. It isn't your website. It is the panel showing your name, address, phone number, hours, services, photos, and client reviews, the information a prospective client sees before they decide whether to contact you at all.
For an insurance agent or broker, the profile is consequential because the search starting a new client relationship often happens at a moment of urgency: a claim, a lapse in cover, a new vehicle, a new business. In that moment, the client isn't browsing websites. They are looking at the map and calling the first practice appearing credible and complete. A profile without reviews, with missing hours, or without a clear list of services tells that client nothing useful. The insurance category is one where search now serves as the primary gateway between providers and new clients, with a growing share of new broker relationships starting on Google Maps rather than through referral. A broker without a verified, maintained profile is absent from that gateway. The setup takes an afternoon; the returns compound over years as your review count grows and your profile gains standing in local search results.
Can I have multiple Google Business Profiles for different insurance products?
No, and attempting to do so risks having all your profiles removed. Google's policy is one profile per physical location. If your brokerage has a single office, it has one profile, regardless of how many lines of cover you offer. The correct approach is to use secondary categories and the services section within a single profile to reflect the range of products you advise on: short-term, commercial, life, and so on.
The exception applies when a brokerage operates from genuinely separate, staffed locations with different addresses. A broker with offices in Sandton and Pretoria can maintain a profile for each, provided each location has its own staff, its own phone number, and operates independently during business hours. Creating two profiles for the same address to target different product searches is against Google's guidelines and is a frequent cause of profile suspension. The safer path is a single, well-maintained profile with complete category and service information covering the full scope of your practice. Your secondary categories carry the differentiation work; the verified address carries the trust signal.
Do I get asked things like "Do you offer specific policy types" in the Q&A section, and how should I handle them?
Yes, and handling them well is one of the simplest improvements most brokers can make. The Q&A section of a Google Business Profile is public: anyone can post a question, and anyone can answer it. If you don't answer your own questions, a well-meaning but inaccurate member of the public might, or the questions sit there unanswered and signal to visiting clients the practice is unresponsive.
The better approach is to seed the Q&A yourself. Consider the five questions your clients ask most often at a first meeting: what types of cover you advise on, whether you handle commercial fleets, what your claims support process looks like, whether you work with a specific insurer panel, and what your office hours are. Post those questions yourself using a personal Google account and answer them from your business account. Each answer should be accurate, specific, and consistent with your FAIS obligations. A populated Q&A section reduces friction for clients comparing you against other brokers on the map and gives Google additional keyword-relevant text to associate with your profile, which supports your visibility for the searches those questions reflect.
What types of groups or clients does a Google Business Profile help me reach?
A well-maintained profile primarily reaches clients searching with local intent: people who want a broker they can call, meet, or speak to on the phone, rather than buying cover through an online aggregator. For South African insurance brokers, this typically means small and medium business owners looking for commercial cover, individuals needing personal lines advice, and clients mid-claim who need an intermediary they can reach directly.
The profile is less effective for reaching large corporate clients, who tend to approach cover through procurement processes and broker panels rather than Google searches. It is also less effective for purely digital product distribution. Where it performs consistently well is the local SME market and the personal lines client who wants a human being rather than a call centre. Those two segments represent the majority of independent broker new business in South Africa, and they are the segments most likely to start their search on Google Maps and call the first broker whose profile gives them a reason to trust the practice before the first conversation. Keeping your profile current, with recent reviews and active posts, is what sustains that advantage as the market grows more competitive.
Yvonne van Wyk
SEO Strategist · Zahavah Studio
Yvonne van Wyk runs Zahavah Studio, a Johannesburg SEO agency focused on long-term search visibility and AI citation. Her writing covers local SEO, content strategy, analytics, and the mechanics of how search works.
Everything on this blog is written to inform and educate. It is for information only. Nothing here is professional legal, financial, or technical advice. If you are making a significant business decision, speak to a qualified professional first. Zahavah Studio works hard to keep this content accurate and current, but is not liable for decisions made based on what you read here.